All Categories
Featured

Future Business Funding Outlook for UK Growth Firms
The UK is especially exposed provided its dependence on gas for electrical power rates, which is why the International Monetary Fund (IMF) has revised its UK inflation and development forecasts more sharply than any other industrialized economy. Inflation briefly dipped below 3% for the very first time because early 2025, however the reprieve will be brief.
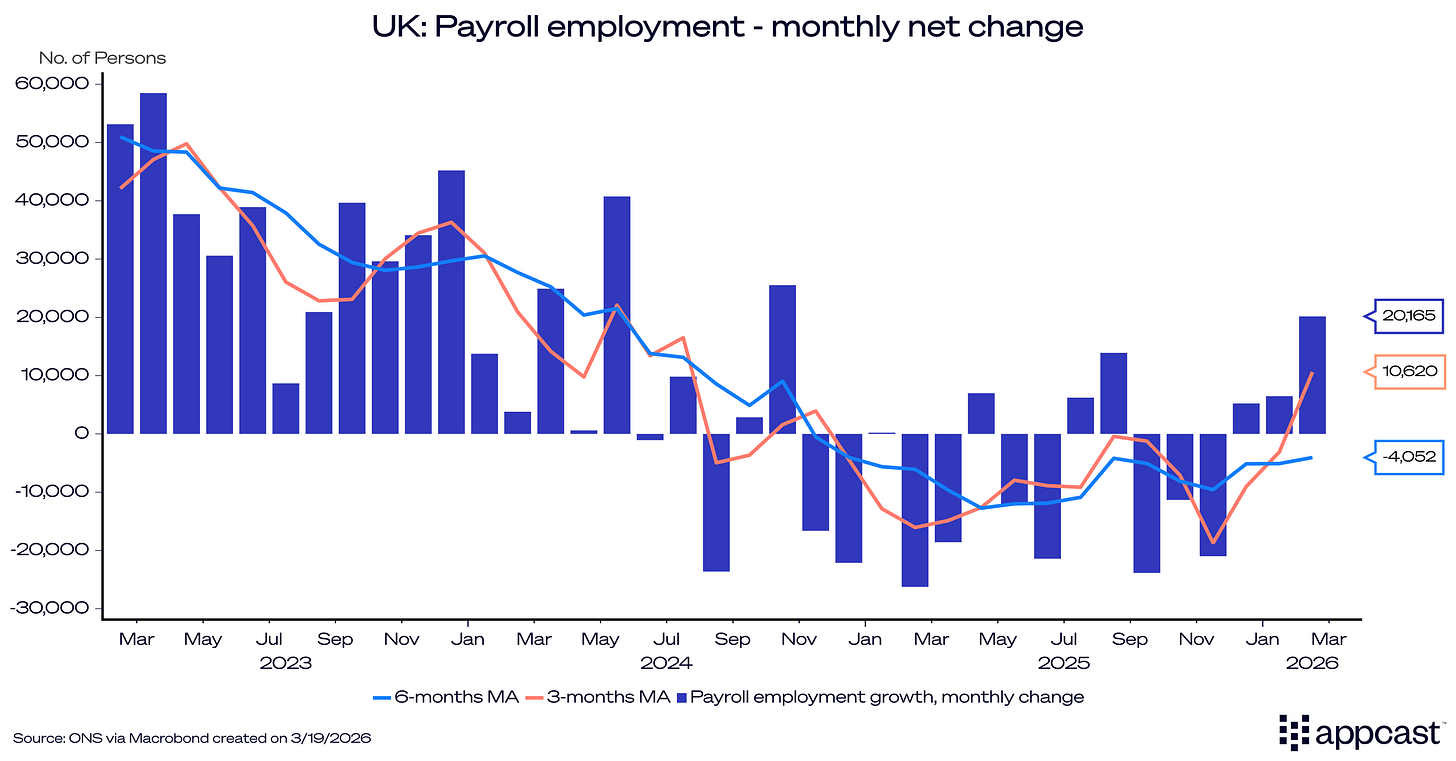
A weaker labour market and softer demand should avoid a repeat of 2022's double-digit spike, restricting second-round effects. Our base case is inflation averaging 3.1% in 2026, peaking around 3.5%, before easing to 2.5% in 2027, though dangers loom large if the Strait of Hormuz stays closed. The UK labour market was already softening before the current energy shock, with unemployment increasing to 5.0% and jobs at their least expensive considering that the pandemic.
Companies are not yet shedding personnel, however unwillingness to employ is widening the space in between task growth and population development. Higher energy expenses will intensify the pressure, and we expect joblessness to peak at 5.3% by year end. With wage growth slowing to around 3.75% and inflation heading towards 3.5%, genuine pay looks set to be stagnant another tough year for living requirements.
Three factors restrict the case for walkings: the energy shock is smaller sized than in 2022, rates are already at a limiting level, and a weaker economy minimizes the threat of second-round inflation impacts. That stated, rate increases can not be ruled out if energy rates rise even more. Gilt yields are likely to remain elevated regardless, driven by the UK's inflation sensitivity and political unpredictability around a possible modification of Prime Minister, keeping loaning costs high across the economy even if the policy rate remain on hold.

Latest Posts
Securing Sustainable Value Through ESG Supply Chains
How AI-Driven Transformation Accelerates UK Efficiency
Reviewing UK Trade Reports for Market Insights